High-risk merchant accounts are specialized payment setups for businesses that face extra underwriting or regulatory scrutiny because of their industry or credit history. Vertical examples include adult entertainment, nutraceuticals, CBD, and online gaming. For companies with damaged credit or industries prone to chargebacks and compliance challenges, knowing how high-risk accounts work is essential to keep sales moving and manage exposure. This guide explains the key features, common industries, advantages for lower-credit businesses, and how to choose the right payment partner.
These accounts exist because some businesses show higher chargeback rates, tighter compliance needs, or more volatile transaction patterns. Understanding high-risk payment mechanics helps merchants stabilize cash flow, limit disruptions, and keep a good relationship with processors. Below we outline core features, industry classifications, benefits for merchants with poor credit, and practical criteria for selecting a provider.
High-risk merchant accounts include capabilities built to handle the specific challenges of risky verticals. These features help protect revenue and keep operations running.
Together, these features let merchants focus on growth while minimizing processing risk.
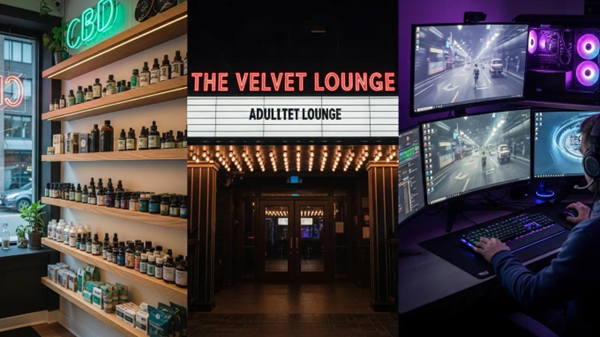
Certain sectors face higher regulatory or chargeback exposure and often require specialized payment arrangements. Identifying where your business fits helps you plan for the right processor and compliance needs.
Understanding your industry’s specific risk drivers is the first step to securing the correct payment solution.
High-risk merchant accounts can open doors for businesses that struggle to qualify for standard processing because of past credit issues. These accounts accept greater underwriting risk while offering practical advantages.
These options let merchants continue accepting payments and rebuild financial credibility over time.
Choosing a processor is as important as choosing a bank. Your partner should understand your industry rules and be transparent about costs and controls.
A careful evaluation ensures the provider supports your operations and long-term growth.
High-risk merchant accounts are payment accounts configured to accept businesses that present elevated underwriting or compliance risk. They matter because they let companies that might otherwise be blocked accept payments, protect against fraud, and meet regulatory requirements. Without them, many businesses would struggle to collect revenue reliably.
High-risk processors use different underwriting, monitoring, and risk-mitigation practices than standard processors. They typically require stricter reporting, higher reserves or fees, and stronger fraud controls to offset increased chargeback and regulatory exposure. Those measures reflect the greater liability processors assume when serving higher-risk merchants.
Industries are labeled high risk when their products, customer behavior, or legal frameworks increase fraud, chargebacks, or compliance obligations. Common examples include:
Knowing these risk drivers helps merchants prepare the documentation and controls processors expect.
Industry-specific high-risk accounts are tailored to the realities of sectors like nutraceuticals and adult gaming. They typically include targeted fraud checks, compliance support, and customized underwriting criteria so businesses can accept payments while meeting regulator and processor expectations.
Nutraceutical sellers face recurring payment issues, including:
These pressures make specialized payment solutions and clear product labeling essential.
Payment solutions for adult gaming focus on compliance and risk reduction. Key capabilities include:
Those controls let businesses operate within strict legal frameworks while reducing fraud exposure.
Merchants with poor credit can improve approval odds by taking steps that build credibility with processors.
Complete documentation and proactive risk controls make underwriters more comfortable approving accounts.
Underwriting for bad-credit high-risk accounts focuses on several areas:
Understanding each provider’s criteria helps merchants meet expectations and speed approval.
Several processors specialize in high-risk merchants. Options to consider include:
Compare capabilities, pricing, and compliance support before choosing a partner.
Effective chargeback and compliance programs combine technology and customer care. Core strategies include:
Proactive monitoring and strong customer service lower dispute rates and protect processor relationships.
Chargeback prevention preserves revenue and reputation. Practical tactics include:
Prioritizing prevention reduces costs and helps maintain long-term processing privileges.
High-risk merchants must meet a mix of regulatory and industry standards that vary by sector and location. Typical obligations include:
Staying current with rules and documenting compliance efforts is essential to avoid fines, account holds, or terminations.
High-risk merchant accounts usually cost more than standard accounts to offset greater underwriting and fraud exposure. Expect transaction fees, monthly gateway or account fees, chargeback fees, and sometimes setup charges. Providers may also require a rolling reserve or security deposit to cover disputes. Review fee schedules closely to understand total cost and avoid surprises.
To improve approval odds, submit a complete, honest application: include business history, clear product descriptions, financial statements, refund and dispute policies, and evidence of fraud controls. Target processors that specialize in your industry and be ready to accept reasonable contract terms—such as reserves or higher fees—during the initial period.
Chargeback management is central to sustaining a high-risk account. High dispute rates can lead to freezes or termination. Effective management includes fraud prevention tools, clear billing descriptors, fast customer service, and documented dispute-resolution workflows. Showing processors you actively control chargebacks improves long-term stability and can reduce fees.
Yes. Regulations vary by industry and jurisdiction but commonly include consumer protection laws, licensing, advertising restrictions, data-security requirements (like PCI compliance), and sector-specific rules (gambling licenses, controlled-substance regulations, etc.). Work with legal and compliance advisors and choose processors who help you meet these obligations.
Specialized processors bring domain knowledge, bespoke fraud and compliance tools, and flexible underwriting mainstream providers often won’t offer. They understand vertical-specific challenges, can advise on best practices, and may accept merchants mainstream vendors decline. That expertise helps merchants accept payments reliably while managing elevated risk.
Maintain current legal guidance, implement documented compliance programs, perform regular audits, and train staff on requirements. Partner with processors that verify compliance measures and provide reporting and monitoring tools to demonstrate ongoing adherence.
Look for transparent pricing, proven vertical experience, strong fraud-prevention features, responsive support, reasonable reserve policies, and clear contract terms. A processor that understands your model and can scale with you is more valuable than the lowest-cost vendor.
High-risk merchant accounts are a practical, often necessary solution for businesses under tighter underwriting or regulatory scrutiny. By understanding features, industry fit, and the benefits—especially for merchants with poor credit—you can pick a partner that supports reliable payments, strong compliance, and steady growth. When evaluating options, prioritize transparent pricing, demonstrated industry expertise, and proven chargeback and fraud defenses to protect your business and revenue.