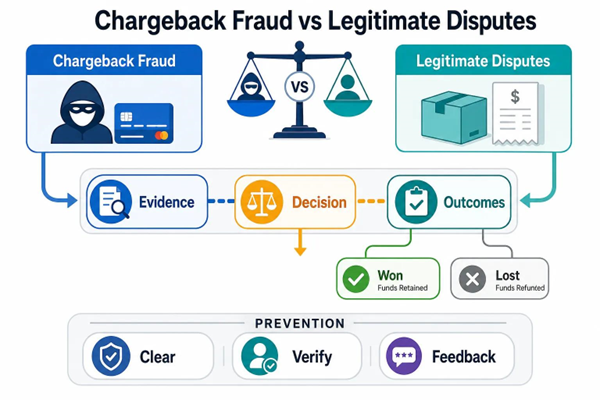
Chargeback fraud and legitimate disputes sit on opposite ends of the same problem: contested transactions. Distinguishing them helps merchants protect revenue and helps consumers assert real rights. Chargeback fraud—often called “friendly fraud”—occurs when a cardholder falsely disputes a valid charge. Legitimate disputes arise from real issues like non‑delivery, product defects, or unauthorized transactions. Below we outline practical, proven strategies to prevent fraud and manage disputes when they occur.
Online commerce increases both genuine disputes and opportunistic chargebacks. Effective defenses combine clearer customer communication, stronger verification, and robust post‑sale processes. The sections that follow define types of disputes, show prevention tactics, explain the typical dispute workflow, and cover legal points merchants should know.
Use this checklist to understand the core differences and to prioritize the controls that reduce losses and improve customer experience.
Chargeback fraud is when a cardholder deliberately disputes a valid transaction to force a refund through their bank. Legitimate disputes are raised for valid causes—items not delivered, damaged goods, or unauthorized activity. Recognizing intent and evidence distinguishes the two, and that distinction drives how merchants respond.
The table below compares characteristics, common causes, and merchant impacts so you can design targeted controls for each scenario.
| Characteristic | Chargeback Fraud | Legitimate Dispute |
| Definition | Intentional or opportunistic false claims to reverse valid charges | Authorized complaints based on service failure or product defects |
| Common Causes | Deliberate abuse, confusion over statement descriptors, or misuse of dispute rights | Non‑delivery, unauthorized charges, damaged or materially different goods |
| Impact on Merchants | Direct financial loss, higher processing fees, and elevated chargeback ratios | Revenue and reputation exposure; legitimate remediation costs if claims are valid |
| Prevention Strategies | Stronger authentication, clearer billing descriptors, and proactive post‑sale outreach | Better fulfillment transparency, straightforward refund policies, and rapid customer service |
Knowing these differences helps merchants apply stronger, more surgical defenses and preserve positive customer relationships when disputes are genuine.
Friendly fraud typically looks like a customer who received their order but later contests the charge, claiming it was unauthorized or never delivered. This behavior is increasingly common in e‑commerce and can represent a large share of chargebacks. Merchants face an uphill battle because they must compile convincing evidence to win representments—so prevention and recordkeeping are essential.
Payment disputes generally fall into three buckets: unauthorized transactions (card misuse or stolen credentials), goods not received (delivery failures or lost shipments), and significantly damaged goods (items materially different from what was promised). Each category requires specific evidence and tailored customer outreach to resolve efficiently.
Preventing chargebacks starts before checkout and continues through delivery and post‑sale support. The strongest programs blend operational controls, customer communication, and technology.
Some proven strategies include:
Equipping staff to recognize dispute signals and document transactions thoroughly is equally important.
To limit friendly fraud, combine transactional analytics with behavioral signals. Real‑time scoring, anomaly detection, and device fingerprinting highlight suspicious orders. Automated alerts let you intervene—confirm addresses, request identity verification, or reach out to customers—stopping many disputes before they become chargebacks.

Adopt a consistent, documented approach to manage chargebacks and preserve merchant credibility.
Systematic processes and clear ownership reduce the time and cost of dispute handling.
Dispute resolution follows a defined path: detection, initial merchant response, issuing bank review, and outcome (merchant wins, issuer reverses, or settlement). Clear timelines and evidence requirements govern each step—missing documentation can doom a representment.
Merchants gather and submit evidence; issuing banks evaluate the cardholder claim; and card networks enforce rules and adjudicate when disputes escalate. Timely, accurate information exchange among these parties is essential for fair outcomes.
Winning disputes depends on thorough, well‑organized evidence: order records, delivery tracking, signed proof of receipt, correspondence logs, and refund attempts. Present documents in the format the processor expects and include a concise timeline and statement of facts to strengthen your case.
Legal rules set the framework for dispute windows, consumer rights, and required documentation. Merchants should understand applicable statutes, industry rules, and card‑network regulations to ensure compliance and mount effective defenses.
Industry reports reveal emerging fraud vectors, changing consumer behavior, and regulatory updates that inform policy adjustments. Use those insights to refine risk rules, update staff training, and prioritize technology investments that address current threats.
Consumer protection laws—like the Fair Credit Billing Act and similar regional statutes—define consumers’ rights to dispute charges and outline merchant obligations. Familiarity with these laws helps merchants set compliant policies and collect legally relevant evidence.
Case studies and data highlight which industries and transaction types are most exposed, which controls work, and the ROI of prevention investments. Use empirical evidence to guide policy and tech choices rather than reacting to isolated incidents.
Recent research shows chargeback and friendly fraud trends rising in many online sectors, though rates vary by vertical and sales channel. Track benchmarks for your industry to set realistic performance targets and justify investments in prevention.
Successful case studies typically combine better customer service, automated evidence workflows, and targeted authentication. They demonstrate that a mix of process improvement and technology produces measurable reductions in chargebacks and faster resolutions.
Structured data and modern tools improve transparency and speed for everyone involved. Proper metadata, clear receipts, and machine‑readable dispute documentation shorten resolution times and improve representment success rates.
Using schema.org markup for financial products and how‑to content helps present clear, machine‑readable information to consumers and search engines. For merchants, structured data can standardize product and policy details used in evidence packets or customer help pages.
AI tools analyze patterns across transactions, devices, and behavior to surface high‑risk orders, automate verification, and prioritize manual review. When tuned correctly, they reduce false positives while preventing many chargebacks before they occur.
Consumers can protect themselves by keeping receipts and order confirmations, monitoring statements regularly, and contacting merchants first to resolve problems. Knowing dispute windows under consumer protection laws and keeping records of communications helps validate genuine claims.
Train teams on the dispute lifecycle, evidence requirements, and common fraud signals. Use practical exercises, runbooks, and regular updates on evolving fraud methods so staff can respond quickly and consistently.
Chargeback management platforms, fraud scoring engines, and CRM integrations streamline tracking, evidence collection, and customer outreach. Machine learning can prioritize cases and automate routine tasks to cut resolution time and cost.
E‑commerce, travel, subscription services, and digital goods often experience higher chargeback risk due to online purchasing, intangible products, and easy dispute initiation. Tailor controls to the specific risk profile of your vertical.
Clear, accessible refund and return policies reduce confusion and give customers a first step to resolve issues. Publish policies at checkout, on order confirmations, and in help centers to lower the chance customers file disputes instead of requesting refunds.
High chargeback rates damage merchant standing with processors, can increase fees, and may lead to account termination. They also correlate with negative customer experiences that harm brand reputation and reduce repeat business.
Review prevention and dispute workflows at least quarterly, and immediately after any spike in chargebacks. Frequent reviews let you adapt to new fraud trends, refine rules, and retrain staff as needed.
Telling fraud apart from valid disputes is essential for protecting revenue and customer trust. A layered approach—clear communication, reliable verification, structured evidence, and the right technology—reduces chargebacks and improves outcomes when disputes arise. Use these best practices to strengthen your defenses and resolve issues faster, protecting both your bottom line and your brand. Contact High Risk Pay Merchants today.