
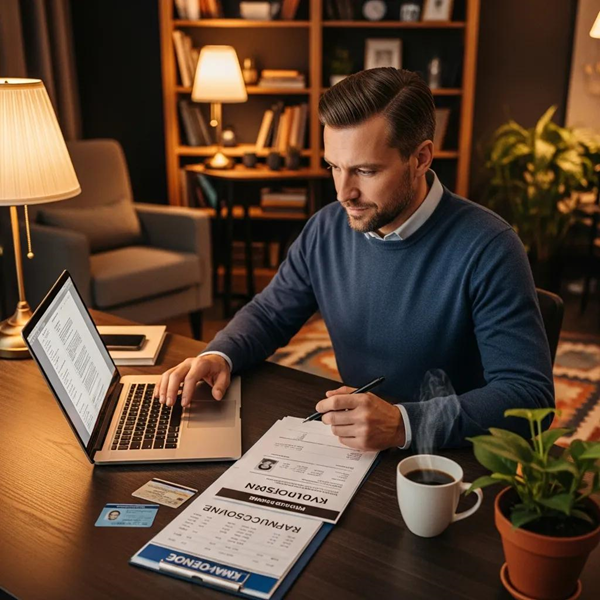
Processors and financial institutions closely review who owns the business or how transactions are handled and whether payment activity creates financial or regulatory risks. That is where KYC, AML, and identity verification become important for high-risk merchants.
These systems help processors reduce fraud exposure by helping businesses to maintain stable payment operations. Without proper verification procedures many merchants face delayed approvals and frozen accounts along with compliance issues later.
At High Risk Pay Merchants businesses need payment solutions that balance stricter compliance requirements with practical day-to-day processing stability.
Know Your Customer requirements help processors verify that a business is legitimate before payment processing begins.
Processors request several forms of documentation during underwriting. Those records help confirm ownership, financial activity, and operational structure before approvals are granted.
Most high-risk merchant applications commonly require:
Business registration documents
Government issued identification
Bank statements
Proof of business address
Processing history
These reviews help processors understand how the business operates and whether transaction activity creates elevated financial risk.
Fraud prevention starts before transactions even happen.
Identity verification systems help reduce fake business applications, unauthorized payment activity, and account misuse. That becomes especially important for industries processing larger transaction volume or international payments.
Processors use verification procedures to confirm identities and monitor suspicious behavior before fraud activity increases.
For merchants stronger verification creates better account stability because processors feel more confident supporting the business long term.
At High Risk Pay Merchants onboarding systems focus heavily on helping businesses complete verification requirements correctly from the beginning to reduce future compliance issues.
Anti-money laundering regulations affect how high-risk businesses process payments globally.
Processors monitor transaction activity closely to identify unusual payment patterns or potentially fraudulent behavior. Businesses operating in higher-risk industries face stronger compliance reviews because financial institutions must follow stricter regulatory obligations.
Failure to meet AML requirements can create serious problems later.
Businesses may face processing restrictions, account closures, financial penalties, or longer underwriting reviews if monitoring systems identify unresolved compliance concerns.
That is why AML preparation matters before payment processing even begins.
Modern payment systems rely heavily on automated transaction monitoring.
Processors use technology to track unusual behavior patterns, transaction spikes, international activity, and potential fraud risks in real time. Businesses processing high transaction volume especially benefit from stronger monitoring because suspicious activity can be identified earlier.
That does not only protect processors.
It also helps merchants reduce disputes, prevent unauthorized payments, and maintain healthier account performance long term.
At High Risk Pay Merchants, payment solutions focus on combining transaction monitoring with practical fraud prevention tools that support long-term processing reliability.
Bad credit history does not always prevent merchant account approval.
Many high-risk processors review the broader business profile instead of relying entirely on personal credit scores. Revenue activity, operational structure, fraud controls, and payment history influence approval decisions alongside credit background.
Businesses with organized applications improve approval outcomes significantly.
That includes providing accurate business records, stable banking details, and transparent transaction information during underwriting reviews.
Alternative processors provide more flexibility for merchants rebuilding financial stability while still needing reliable payment processing access.
Simple document reviews are no longer enough for many processors.
Identity verification systems now include additional security measures designed to reduce fraud exposure further. Multi-factor authentication, behavioral monitoring, and biometric verification tools are increasingly used across payment platforms to protect transaction activity.
Those systems help reduce:
Account takeovers
Unauthorized transactions
Identity fraud
Payment abuse
For high-risk businesses, stronger identity verification improves processor confidence while reducing operational risks tied to fraud disputes later.
Verification requirements do not stop after account approval.
Processors may request updated records if ownership changes, transaction activity increases, or business models shift Merchants that fail to maintain accurate records sometimes experience payout delays or additional compliance reviews later.
Regular updates help businesses maintain smoother processor relationships while reducing unnecessary account interruptions.
That ongoing maintenance has become a normal part of modern high-risk payment processing.
High-risk payment processing requires more than basic account approval.
Businesses need payment systems that support verification requirements and transaction monitoring without creating unnecessary operational problems.
High Risk Pay Merchants focuses on helping businesses manage KYC, AML, and identity verification requirements and maintain stable payment processing across higher-risk industries.
Solutions are structured around compliance readiness, fraud prevention, and long term account reliability instead of temporary approvals alone.
That approach helps businesses reduce payment interruptions while building stronger processor relationships
If your business needs support with merchant verification, AML requirements, or high-risk payment processing, High Risk Pay Merchants can help you review payment solutions built for compliance and long-term transaction stability.
Processors commonly request business registration documents with your identification records along with address proofs and bank statements.
AML helps processors monitor suspicious transaction activity and reduce financial crime risks.
Yes. Some high-risk processors evaluate overall business performance alongside credit history during underwriting.
Verification systems safegard from fake accounts or unauthorized transactions and payment abuse.
Processors may require updated records when ownership details and transaction activity along with operational structure changes
WhatsApp us