Best 0% APR Business Credit Cards for Small Businesses in 2026
Managing business expenses becomes difficult when cash flow feels tight during few months. Equipment purchases, inventory costs, software subscriptions, and operational spending can quickly create financial pressure for growing businesses trying to scale carefully.
This is one reason many businesses look for 0% APR business credit cards.
A good 0 APR business credit card gives businesses temporary flexibility without immediate interest costs. Instead of paying large expenses upfront companies get time to spread payments across the introductory period while protecting short-term cash flow.
For businesses planning carefully these cards are becoming less about convenience and more about financial timing and smarter operational control.
What Is a 0% APR Business Credit Card?
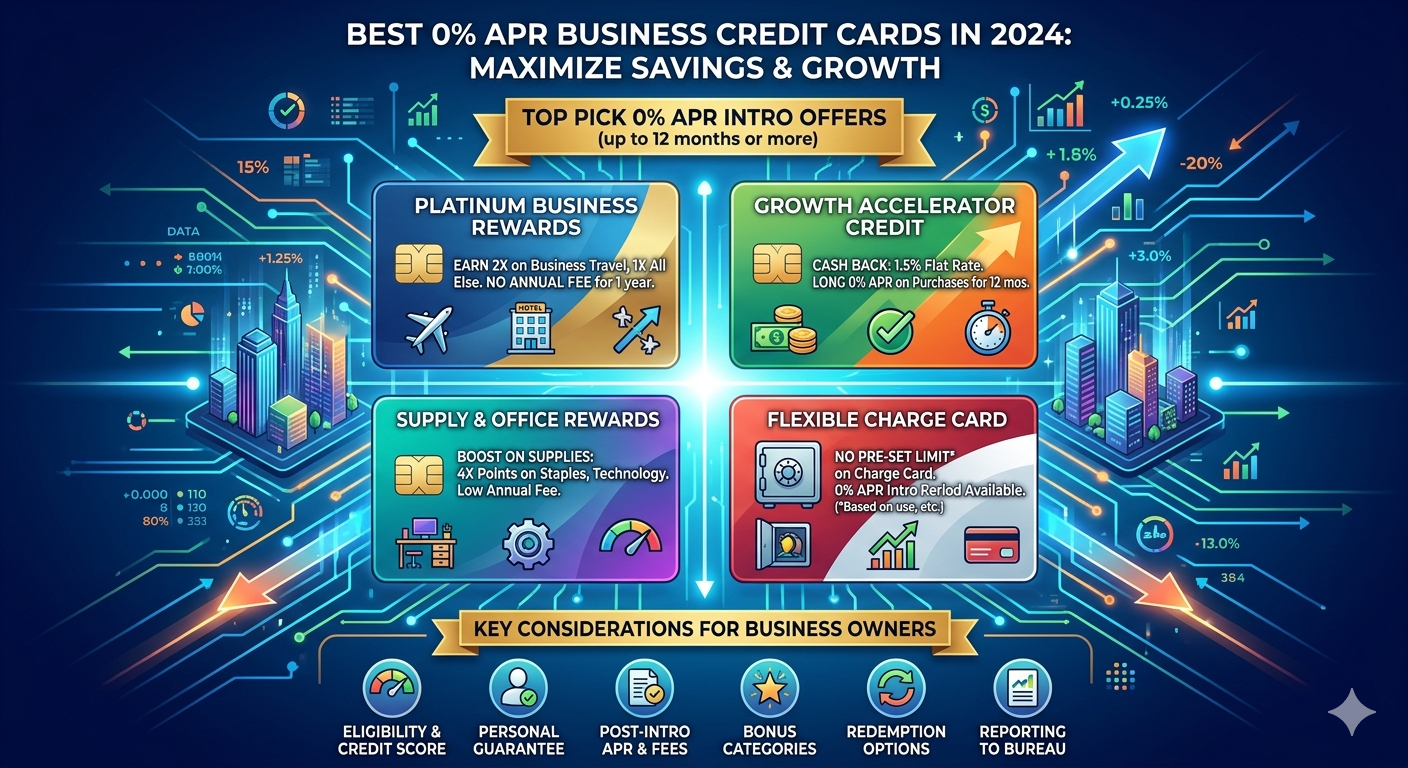
A 0% APR business credit card offers an introductory period where interest is not charged on purchases and balance transfers or sometimes both.
That promotional period may last several months depending on the provider and card structure.
During that time, businesses can:
- Handle operational purchases
- Transfer higher-interest balances
- Invest in growth-related expenses
- Manage temporary financial gaps
- Protect working capital
The main advantage is simple. Businesses get time to repay expenses before standard interest rates begin applying.
Why Businesses Use 0 APR Business Credit Cards in 2026
Business owners are becoming more cautious with cash flow management.
Instead of taking larger loans immediately many businesses now prefer short-term financing tools that provide flexibility without long-term debt pressure.
A 0 APR business credit card helps businesses stay operational while maintaining liquidity for more important expenses.
This becomes especially useful during:
- Seasonal revenue fluctuations
- Expansion periods
- Inventory purchasing cycles
- Unexpected operational costs
- Marketing or hiring investments
For newer businesses, it can also reduce pressure during early growth stages where revenue is still stabilizing.
Large Business Purchases Become Easier to Manage
Many businesses avoid necessary purchases because immediate full payment affects operational cash flow.
That delay slows growth.
A 0 APR business credit card gives businesses more room to handle larger purchases without immediate financial strain.
Common business uses include:
- Office equipment upgrades
- Technology purchases
- Inventory restocking
- Software subscriptions
- Business setup costs
The advantage is not avoiding payment. It is creating time to repay strategically without interest building immediately.
Balance Transfers Can Reduce Existing Interest Costs
Businesses carrying balances on high-interest cards lose money every month through unnecessary interest charges.
Balance transfer offers connected to 0 APR cards help reduce that financial pressure temporarily.
This allows businesses to:
- Consolidate debt more efficiently
- Simplify monthly repayments
- Reduce short-term interest costs
- Improve financial organization
However, businesses should still review transfer fees carefully before making decisions.
Cash Flow Stability Matters More Than Most Businesses Realize
Many businesses fail because of cash flow problems rather than lack of revenue.
Operational timing matters.
A business may be profitable overall while still struggling during temporary slow periods.
A 0 APR business credit card helps create short-term breathing room so businesses can continue operating without disrupting essential expenses.
That flexibility helps businesses:
- Cover recurring operational costs
- Handle delayed customer payments
- Manage supplier expenses
- Continue growth investments
The key is maintaining a structured repayment plan before the introductory period ends.
Things Businesses Should Check Before Choosing a Card
Not all 0 APR business credit cards work the same way.
Many businesses focus only on the promotional period while ignoring long-term costs or restrictions attached to the card.
Before applying, businesses should review:
Introductory APR Duration
Some cards offer shorter promotional windows while others extend much longer.
A longer period provides better repayment flexibility.
Standard Interest Rate After Promotion
Once the promotional period ends, regular APR begins applying.
Businesses should understand those rates beforehand to avoid future financial pressure.
Balance Transfer Costs
Some providers charge transfer fees between 3% and 5%.
Those fees may affect whether transferring balances actually saves money overall.
Rewards Structure
Some cards include cashback or travel rewards tied to operational spending categories.
Businesses benefit more when rewards align naturally with their existing expenses.
Annual Fees
Cards with strong rewards sometimes include annual costs.
Businesses should compare whether the long-term value actually justifies those fees.
Smart Ways Businesses Use 0 APR Business Credit Cards
Businesses using these cards strategically focus on operational timing rather than unnecessary spending.
Practical uses include:
- Inventory purchasing before seasonal demand
- Marketing campaigns during growth periods
- Temporary emergency repairs
- Hiring-related expenses
- Software or technology upgrades
The card becomes a short-term financial management tool rather than revolving debt when used correctly.
Common Mistakes Businesses Should Avoid
Many businesses misuse promotional APR offers because they focus only on temporary flexibility.
That creates larger problems later.
Common mistakes include:
- Ignoring repayment deadlines
- Carrying balances after promotional periods end
- Making unnecessary purchases
- Missing monthly payments
- Depending too heavily on revolving credit
A 0 APR offer only works properly when repayment planning already exists before spending begins.
How 0 APR Business Credit Cards Affect Business Credit
Responsible usage can help businesses build stronger credit profiles over time.
Consistent payments and controlled utilization improve overall business credit health.
That may later support:
- Better financing approvals
- Higher credit limits
- Lower financing costs
- Improved lender confidence
Poor management, however, creates the opposite effect. Businesses should treat promotional credit carefully rather than as unlimited spending access.
Why 2026 Businesses Are Using Flexible Credit More Strategically
Businesses today operate in less predictable financial environments.
Operational costs fluctuate more often. Revenue cycles change faster. Many businesses now prioritize flexibility over long-term financing commitments.
That shift is one reason 0 APR business credit cards continue growing in popularity during 2026.
When managed carefully, they provide short-term stability without creating immediate financing pressure.
Conclusion
A 0% APR business credit card can be a useful financial tool for businesses that need temporary flexibility without immediate interest pressure. The real advantage comes from better timing with stronger cash flow management and more controlled operational spending.
Businesses that use these cards strategically gain short-term financial breathing room while protecting working capital for more important priorities.
The most important step is careful planning. Businesses should understand promotional terms fully and create a repayment strategy before using the available credit.
High Risk Pay Merchants provides business payment solutions designed to support smoother financial operations and better payment management.
FAQs
What is a 0 APR business credit card?
It is a business credit card offering a temporary introductory period where no interest applies on purchases or balance transfers.
How long do 0 APR offers last?
The promotional period varies depending on the provider and card type.
Are balance transfers worth using?
They can reduce short-term interest costs if businesses repay balances before standard APR begins.
Can startups apply for 0 APR business credit cards?
Yes. Approval depends on business financials, personal credit history, and overall application strength.
What happens after the promotional period ends?
Regular interest rates begin applying to any remaining balance.
Do 0 APR business cards help build business credit?
Responsible usage and consistent payments may improve business credit over time.